
The China+1 narrative is structurally real but operationally narrower than the consensus packaging suggests. The dominant framing treats it as a binary question — “China or not China” — when the actual problem is portfolio optimization: which functions of the supply chain you concentrate where, and what risk you are willing to hold in exchange for what you get back.
The real constraint is not unit cost. It is supplier density.
What China Actually Provides as a Node
The “cheap labor” arbitrage closed years ago. Average manufacturing wages in China now run $6.50–$7.50/hour, while Mexico sits around $4.82/hour. For labor-intensive categories, China is no longer the cheapest option.
What China still offers is something that does not relocate on a tariff timeline: supplier density. Thousands of qualified sub-tier vendors within a day’s drive of each other. Component and tooling depth that took decades to build. Engineering talent that can iterate from prototype to volume faster than almost any alternative. Infrastructure and scale that lets you compress what would be a two-year ramp in a new country into months.
That is why “just leave” keeps failing as a strategy. The constraint is physical, not political.
The Diversification Illusion
The most common failure mode of China+1 is treating a third country as a substitute for China when it is actually a downstream customer of China.
Vietnam imports at least half of its raw manufacturing materials from China. Cambodia relies on China for roughly 60% of its garment inputs. Academic trade data confirms this at the macro level — exporters that have replaced China in the U.S. market have also increased their own import dependence on China.
“Diversification” often just moves the visible node, not the actual dependency. You add a processing step over Chinese inputs, take on extra freight and rules-of-origin scrutiny, and call it resilience. The risk has not been shed; it has been rerouted.
Fallback vs. Dual-Sourcing: The Distinction Matters
The China+1 spectrum maps to fundamentally different operating models, and conflating them produces bad capital allocation.
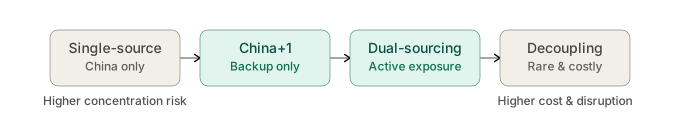
China+1 as fallback is insurance. You keep a second qualified line mostly idle, ready to absorb volume if China becomes unavailable or uneconomical. The daily cost is low, but the backup is under-utilized and under-tested. When you actually need it, it may not be ready.
Dual-sourcing with strategic Chinese exposure is a deliberate allocation, not a hedge. You decide, by product category, what stays in China — usually the parts requiring deep component ecosystems, tooling, and fast engineering iteration — and what moves out — usually labor-intensive final assembly or lower-complexity SKUs. This is closer to where sophisticated operators actually are in 2026. It is a risk diversification strategy, not an exit plan. Less about cost arbitrage, more about resilience, continuity, and strategic flexibility.
Complete decoupling is mostly rhetoric outside a few strategic categories — advanced semiconductors, certain defense-adjacent technology, critical minerals in some jurisdictions — where governments, not commercial logic, force it via export controls. Commercially, full decoupling from China is not happening. What is happening is selective diversification.
The economic case against blanket decoupling is substantial. We estimate that the trade-channel cost alone would be $190 billion in foregone U.S. GDP annually if 25% tariffs were expanded to all two-way trade. There would also be potential one-time GDP losses of up to $500 billion from an investment-channel unwind.
The Hidden Costs That Get Underweighted
The most systematic failures in China+1 execution come from comparing the wrong numbers.
Landed cost, not unit cost. The U.S. win rate against China jumps from 8% when comparing on price alone to 32% when factoring in total cost of ownership. Most sourcing decisions based on headline unit price are miscalibrated. The real number is what the part costs to deliver, qualify, and maintain in production — not what it costs to make.
Ramp time is long and rarely priced in. Setting up viable manufacturing in a new country typically takes one to two years: factory qualification, supplier development, logistics setup, quality system alignment. New countries rarely have China’s depth of upstream supply chain support. The business case usually assumes Day 1 volume at Day 1 yield, which is not how manufacturing works.
Loss of scale and scope economies. Splitting volume across two or three sites means smaller batch runs, weaker supplier leverage, and duplicated tooling and quality systems. This is a real, recurring cost that rarely shows up in the initial business case.
Coordination overhead. Managing quality, IP protection, and supplier relationships across multiple countries and time zones is a genuine operating tax, not a one-time setup cost. It compounds with every additional node.
Policy reversal and stranded-asset risk. Investment decisions made in response to today’s tariffs or politics can look wrong in 18 months if the policy shifts. The direction of policy is not a fixed variable — it is the most volatile input in the equation.
The Framework: Segment by Product, Not by Country
The correct operating model is to treat China+1 as a portfolio problem and segment by product function, not by geography.
Commodity, labor-intensive, lower-IP items are good candidates for real relocation. Wire harnesses, basic stamping, simple assembly — these are where the nearshoring math works because freight cost and tariff exposure matter more than scale economies.
Complex, component-dense, fast-iterating products are where China stays the dominant node for the foreseeable future. Advanced electronics, EV batteries, semiconductors — these depend on specialized manufacturing ecosystems that took decades to build and do not relocate on a tariff timeline. Your “plus one” here is really a controlled, monitored exposure, not a fallback you hope never gets used.
Reserve true decoupling logic for the narrow slice where a government, not your P&L, is making the decision for you. Export controls, national security reviews, critical mineral restrictions — these are where the state overrides commercial logic. Outside that slice, the math is the math.
A Portfolio Problem, Not a Binary Switch
China+1 is not an exit strategy. It is a portfolio optimization problem that most operators are solving incorrectly.
The real constraint is supplier density, not unit cost. China’s evolution from assembly floor to advanced manufacturing hub is not a narrative — it is the structural reality that makes “just leave” fail as a strategy. Diversification that does not actually shed Chinese input dependence is just rerouted risk with extra freight.
The hidden costs of diversification — ramp time, scale loss, coordination overhead, policy reversal — are systematically underweighted in the initial business case. When you factor them in, the China+1 math narrows considerably.
The correct framework is to segment by product function, not by country. Commodity and labor-intensive categories are where real relocation works. Complex and component-dense categories are where China stays the dominant node and your “plus one” is controlled exposure. Complete decoupling is rhetoric outside the narrow slice where the state overrides commercial logic.
The winners are the companies executing that segmentation — the ones that understand which functions belong where and price the real costs of diversification. The losers are the ones treating China+1 as a binary migration rather than a constrained optimization problem.